

Easiest Jewelry Financing: Your Guide to Stress-Free Sparkle
The Truth About Easiest Jewelry Financing (And What to Watch Out For)

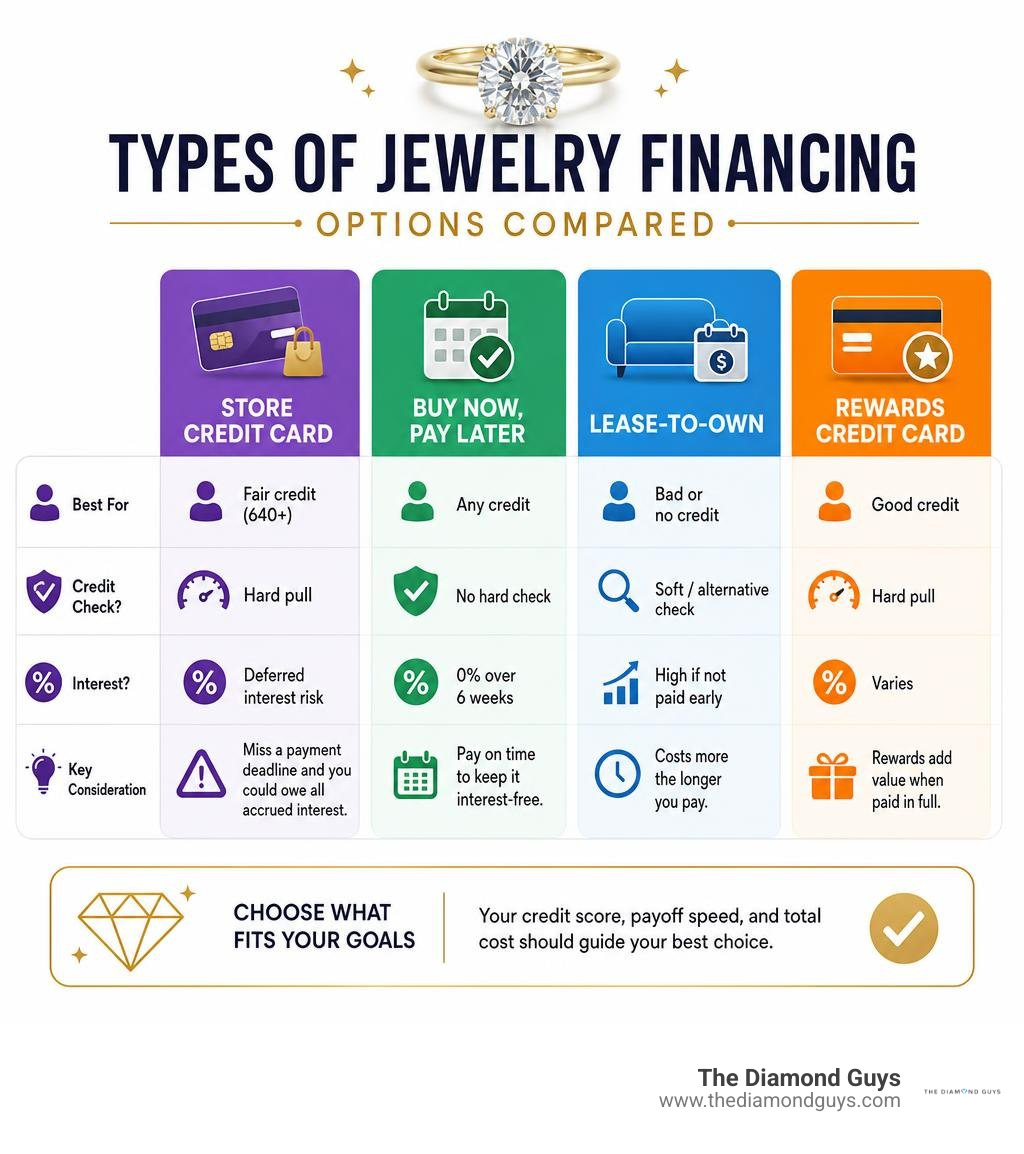
Finding the easiest jewelry financing comes down to matching your credit situation to the right option. Here's a quick breakdown:
| Financing Type | Best For | Credit Check? | Interest? |
|---|---|---|---|
| Store Credit Card | Fair credit (640+) | Hard pull | Deferred interest risk |
| Buy Now, Pay Later (e.g., Sezzle) | Any credit | No hard check | 0% over 6 weeks |
| Lease-to-Own (e.g., Snap Finance) | Bad or no credit | Soft/alternative check | High if not paid early |
| Rewards Credit Card (e.g., Chase Sapphire) | Good credit | Hard pull | Varies |
The right choice depends on your credit score, how quickly you can pay, and how much the total cost matters to you.
Jewelry financing feels exciting — until the bill arrives. Store cards promise easy approvals and 0% interest, but many hide a costly trap in the fine print. Miss the payoff deadline by even one day, and you could owe all the interest that built up from day one. That's not a penalty — it's just how those deals are designed.
Whether you're buying an engagement ring or a gold chain, understanding your options before you apply can save you hundreds of dollars and a lot of stress.
I'm Morgan Price, and I've spent years researching how consumers navigate credit and financing decisions — including the easiest jewelry financing routes that actually protect your wallet. In the sections below, I'll walk you through every major option, the risks to avoid, and the smartest path forward.
What is the Easiest Jewelry Financing Option Available?
When looking for the easiest jewelry financing option, it is easy to feel overwhelmed by the sheer volume of choices. The "easiest" path depends heavily on what you are trying to achieve: is it the easiest to get approved for with a low credit score, or the easiest on your monthly budget?
At The Diamond Guys, we understand that purchasing a major piece of jewelry—whether it is a custom engagement ring or a timeless diamond necklace—is a significant emotional and financial milestone. Providing our clients in Scottsdale, AZ, and Los Angeles, CA, with clear, transparent guidance is at the heart of what we do. We believe you should never have to compromise on quality or ethical standards just to secure a flexible payment plan.
To find the right path, you first need to understand the landscape of Jewelry Financing. Traditional financing options typically involve store-branded credit cards, while modern alternatives offer flexible buy now, pay later (BNPL) structures. If you are shopping around, finding a Jewelry Store With Payment Plan that aligns with your financial health is the ultimate goal. By exploring different structures, you can find the perfect balance of financial flexibility without putting your credit at risk.
Understanding Store Credit Cards and Credit Score Requirements
For decades, store credit cards were the default choice for anyone looking to finance a luxury purchase. If you have ever stood at a retail jewelry counter, you have likely been offered a store card to "save 10% today" or unlock a "0% interest promotional period."
Before you hand over your ID, it is essential to understand how these cards evaluate your creditworthiness. Most traditional jewelry store credit cards require at least a fair credit score (typically 640 or higher) for approval. When you submit an application, the issuer performs a hard credit pull, which temporarily lowers your credit score by a few points.
While store credit cards are relatively easy to qualify for compared to premium rewards cards, they come with lower credit limits and significantly higher standard interest rates once the promotional period ends.
Easiest Jewelry Financing via Store Cards
If you decide that a store card is the right path for you, some options are widely recognized as the easiest to get. Cards issued by major specialty lenders—which handle financing for national jewelry chains—are popular because they regularly approve applicants with fair credit.
While a credit score of 640 is the standard benchmark for these cards, there are real-world instances of applicants with credit scores in the mid-500s securing approvals with modest credit limits (such as $3,000). However, keep in mind that these lenders do not typically offer online pre-approvals for these cards without a hard credit pull. If you are looking to buy a significant piece, like an engagement ring, it is worth researching if you Can You Finance Engagement Rings through other, less risky avenues before committing to a hard credit inquiry.
The Hidden Trap of Deferred Interest
The single biggest danger of utilizing store credit cards for the easiest jewelry financing is a financial mechanism known as deferred interest.
Many store cards advertise "0% APR for 12 months." To the average consumer, this sounds like an interest-free loan. However, deferred interest is entirely different from a true 0% APR credit card. Under a deferred interest agreement, if you fail to pay off the entire balance by the very last day of the promotional period, interest is retroactively applied to your account from the original purchase date.
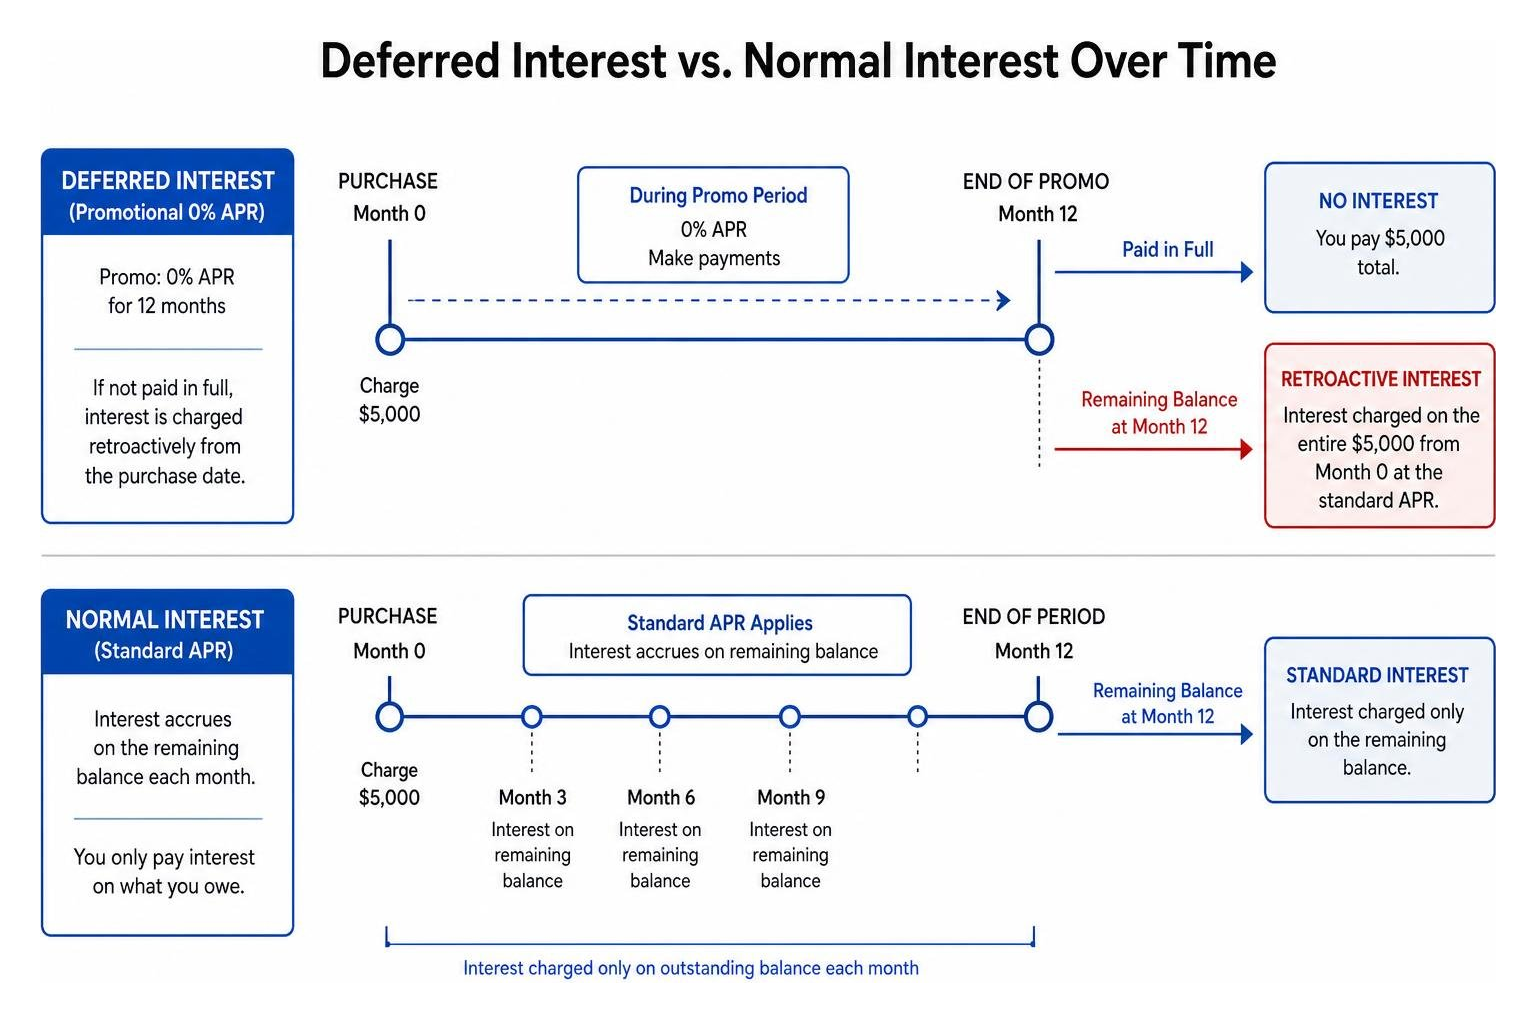
For example, if you finance a $5,000 engagement ring and have a remaining balance of just $100 when the 12-month promotional period expires, you will not just pay interest on that remaining $100. Instead, you will be charged retroactive interest on the full $5,000 starting from day one, typically at an annual percentage rate (APR) of 25% to 30%. This hidden trap can instantly add over a thousand dollars to the cost of your jewelry. To protect yourself, you must establish a strict, aggressive repayment plan to ensure the balance is entirely cleared well before the promotional window closes.
Buy Now, Pay Later (BNPL) as a Flexible Alternative
If you want to avoid the high-interest risks of traditional store credit cards, Buy Now, Pay Later (BNPL) services have emerged as an incredibly popular and consumer-friendly alternative.
| Feature | Store Credit Cards | Buy Now, Pay Later (BNPL) | Lease-to-Own |
|---|---|---|---|
| Credit Score Required | Fair (640+) | Poor to Excellent | No Credit Needed |
| Credit Check Type | Hard Pull | Soft Pull | Soft / Alternative |
| Interest Rate (APR) | 0% Promo, then 25%-30%+ | 0% (for short-term plans) | No interest, but high lease fees |
| Payment Structure | Monthly Minimums | Fixed Installments (e.g., 6 weeks) | Bi-weekly or Monthly |
| Risk of Retroactive Interest | High (Deferred Interest) | None | None (But high overall cost) |
BNPL platforms split your purchase into predictable, bite-sized installments, allowing you to maintain financial control without taking on long-term revolving debt.
Easiest Jewelry Financing with No Hard Credit Check
One of the most accessible BNPL options on the market is Sezzle. Through services like Buy Now Pay Later for jewelry | Split Payments No Interest , shoppers can split their jewelry purchases into four interest-free payments spread over six weeks.
The primary benefit of using Sezzle is that it requires no hard credit check, meaning you can secure approval instantly without hurting your credit score. Sezzle also offers a unique virtual card feature. By downloading the app, you can generate a single-use virtual card to shop at virtually any jewelry retailer that accepts Visa, even if they do not natively partner with the platform.
This level of flexibility makes BNPL an exceptional tool for couples planning their weddings. For a deeper look at budgeting for your big day, check out our Wedding Ring Sets Financing Ultimate Guide.
Lease-to-Own Programs for Bad Credit or No Credit
For individuals with poor credit or no established credit history, traditional credit cards and standard BNPL options may still feel out of reach. In these situations, lease-to-own programs offer a viable pathway to acquiring high-quality jewelry.

Lease-to-own programs do not operate like traditional loans. Instead of borrowing money to purchase the item, you are essentially renting the jewelry from the leasing company with the option to purchase it outright over time.
How Lease-to-Own Agreements Work
Lease-to-own providers look beyond traditional credit scores, making them an incredibly accessible option for bad credit. However, this accessibility comes at a cost. If you let a lease-to-own agreement run to its maximum term—which typically lasts 12 to 18 months—the total cost of ownership can be nearly double the original retail price of the jewelry.
To make lease-to-own financially viable, you must utilize the early buyout option, typically structured as a 100-day option. If you pay off the lease within this initial window, you can avoid the steep leasing fees.
For instance, if you finance a $1,250 jewelry purchase through a provider like Jewelry Financing with Bad Credit | Snap Finance , a standard 36-payment bi-weekly schedule at $74.35 would result in a total cost of $2,487.50. However, by clearing the balance within the first 100 days, you keep your costs close to the original retail price.
Similarly, platforms offering Nuragold Jewelry Financing | Lease to Own & Buy Now Pay Later allow you to finance popular gold items, such as Miami Cuban link chains, with manageable monthly payments, welcoming those with less-than-perfect credit.
Smart Strategies to Afford Your Dream Jewelry
While looking for the easiest jewelry financing is a practical step, the smartest financial strategy is often to leverage existing assets or plan ahead.
If you have good credit, using a general rewards credit card can be far more lucrative than applying for a store credit card. Premium travel cards, such as the Chase Sapphire Preferred, often feature high sign-up bonuses (for example, earning 75,000 bonus points after spending $5,000 in the first three months). By purchasing an engagement ring or fine jewelry on a rewards card, you can instantly secure enough points to fund your honeymoon flights or hotel stays.
Additionally, combining a structured savings plan with a smaller financing portion can keep you out of high-interest debt entirely. We always recommend reading our guide on How To Afford Your Dream Engagement Ring and exploring our Diamond Jewelry Financing Guide 2026 to build a personalized strategy that keeps your purchase joyful and stress-free.
Frequently Asked Questions about Jewelry Financing
What credit score is needed for most jewelry store credit cards?
Most major jewelry store credit cards require a fair credit score, which is typically a score of 640 or higher. While some issuers may approve applicants with scores in the mid-to-high 500s, these approvals often come with lower credit limits and higher interest rates.
Does applying for jewelry financing hurt your credit score?
Applying for a traditional jewelry store credit card or a personal loan involves a hard credit pull, which will temporarily lower your credit score by a few points. However, alternative financing options like BNPL services (such as Sezzle) or lease-to-own programs typically perform soft credit checks that do not impact your credit score.
Can you finance an engagement ring with bad credit?
Yes. If you have bad credit or no credit, you can finance an engagement ring using lease-to-own programs or alternative financing platforms. To avoid high overall costs, always aim to pay off the balance within the promotional early buyout period (usually 90 to 100 days).
Conclusion
At The Diamond Guys, we believe that buying beautiful jewelry should be an exciting, memorable experience—not a source of financial anxiety. Whether you are searching for custom engagement rings, GIA-certified natural diamonds, or stunning lab-grown diamonds, our team in Scottsdale, AZ, and Los Angeles, CA, is here to provide expert, transparent guidance every step of the way.
We prioritize ethical sourcing and a highly personalized shopping experience, ensuring you get the absolute best value for your budget. Before you sign up for a high-interest store card with hidden traps, we invite you to Explore flexible financing options at The Diamond Guys and let us help you find a payment path that keeps your financial future as bright as your new sparkle.


